Mutual Fund Distribution:
Mutual funds have become an important investment instrument for individuals seeking professionally managed and diversified investment opportunities. They can provide access to a broad range of securities through a pooled investment structure, making them useful for investors who may not have the time, knowledge, or resources to build and monitor a diversified portfolio of securities by themselves.
However, mutual funds are not risk-free investments. Different mutual fund categories carry different levels and types of risk. Therefore, successful mutual fund investing requires understanding the investor’s financial goals, investment horizon, risk tolerance, liquidity requirements, and the characteristics of the selected scheme.
From a financial-planning perspective, the objective is not simply to choose a mutual fund with high historical returns. The objective is to select an appropriate category and investment strategy that fits a clearly defined financial goal.
What Is a Mutual Fund?
A mutual fund is an investment vehicle that pools money from multiple investors and invests the collected funds in securities according to the scheme’s stated investment objective. Depending on the Mutual Fund scheme, the portfolio may invest in:
- Equity shares
- Government securities
- Corporate bonds
- Money-market instruments
- Gold-related assets
- Other permitted securities
The fund is managed by professional investment managers according to the scheme’s mandate. This structure allows an investor to participate in a diversified portfolio without having to individually purchase every security held by the fund.
Importance of Mutual Funds in Financial Planning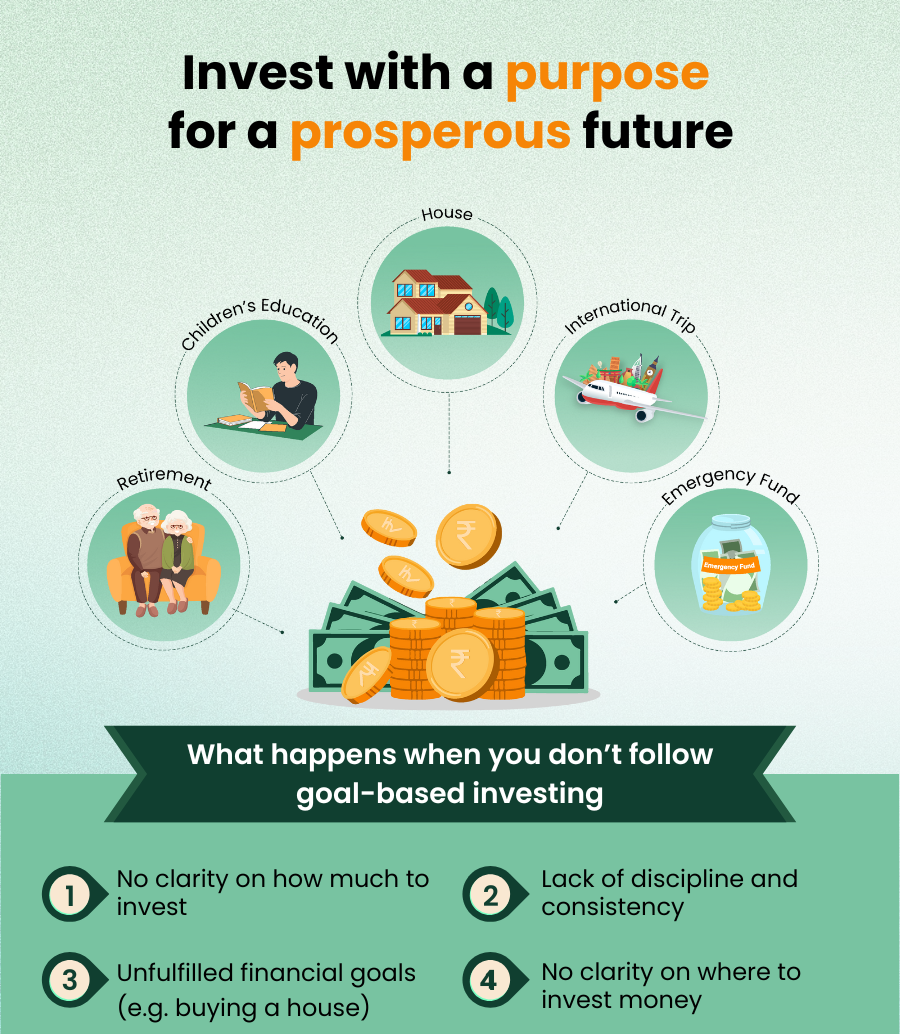
In Financial Planning, Mutual Funds took a key role for investments to grow and achieve the financial goals due to certain advantages –
- Transparency – An investor is well served if relevant information is available on time. Availability of such information is critical for making an informed investment decision.
- The structure of the mutual funds and the regulations by SEBI have ensured that investors get such transparency about their investments.
- There are three essential places from which the investor can get enough information for making informed decisions, viz., scheme related documents (SID, SAI, and KIM), portfolio disclosures, and the NAV of the scheme.
- Incidentally, even a prospective investor can access all this information.
- Economies of Scale – Pooling of large funds from many investors makes it possible for the mutual fund to engage professional managers for managing investments which is not possible for an individual investor.
- Mutual funds give the flexibility to an investor to organize their investments according to their convenience.
- The Income Distribution cum Capital Withdrawal (IDCW) and growth options of mutual funds allow investors to structure the returns from the fund in the way that suits their requirements.
- Thus, investing through a mutual fund offers a distinct economic advantage to an investor as compared to direct investing in terms of cost saving.
- Diversification – Diversification is one of the major advantages of mutual funds. Instead of investing all money in a single security (share), a mutual fund can spread investments across multiple securities according to its investment strategy. For example, an equity mutual fund may invest in shares of companies across different industries and market segments.
- Diversification can reduce the impact of poor performance of an individual share though it cannot eliminate all investment risk.
- Professional Management – Many investors do not have the time or expertise to research companies, analyse financial statements, monitor markets, and make portfolio decisions. Mutual funds provide professional portfolio management.
- AMC Fund managers and their investment teams conduct research and make investment decisions according to the scheme’s objectives.
- Accessibility – Mutual funds provide investors with access to different asset classes and investment strategies through relatively easy and accessible investment amounts, depending on the scheme and platform.
- This can make diversified investing easier for many individuals.
- Goal-Based Investing – Mutual funds can be incorporated into different financial goals depending on the fund category and investment horizon. Potential goals may include: Children’s education, Wealth creation, Retirement planning, House purchase, Long-term financial independence, Other planned financial objectives.
- The mutual fund scheme should be selected after identifying the goal.
- Systematic Investment Approach – Systematic Investment Plan, commonly known as SIP, allows investors to invest a predetermined amount at regular intervals in mutual fund scheme.
- SIP can encourage: Financial discipline, Regular investing, Long-term participation, Goal-oriented saving.
- This results investing at different market levels and result in purchasing units at different prices and thus reduces the average cost of investing.
- Liquidity & Safety – Depending on the structure of the mutual fund scheme, liquidity is possible either as and when required (Open Ended), or during specific intervals (Interval Schemes), or only on the closure of the scheme (Closed Ended).
- Close Ended Shemes are compulsorily listed on a stock exchange.
- In such schemes, the investor can sell the units through the stock exchange platform to recover the prevailing value of the investment.
- This combination of transparency and liquidity in MF enhances safety.
- Tax benefits – Specific schemes of mutual funds such as Equity Linked Savings Schemes (ELSS) give investors the benefit of deduction of the amount subscribed up to Rs. 150,000 in a financial year under Section 80C of the Old Tax Regime, from their income that is liable to tax. This reduces their taxable income, and therefore the tax liability.
Risks in Mutual Funds
A common misconception is that mutual funds are inherently safe because they are professionally managed. In reality, mutual funds carry investment risk, and the level of risk varies significantly between categories. For example:
- Equity funds generally have higher market volatility.
- Debt funds may face interest-rate and credit risks.
- Hybrid funds combine different asset classes and therefore have a different risk profile.
- Commodity-oriented funds may be affected by commodity-price movements.
Investors should therefore evaluate the risk of the specific scheme before investing. These risks are –
- Market Risk – Market risk is the possibility that the value of securities held by a mutual fund may decline due to market movements. Equity-oriented funds can experience substantial fluctuations during periods of market uncertainty. Market risk cannot be completely eliminated.
- Equity Risk – Equity mutual funds invest substantially in shares or equity-related securities. Their value may fluctuate due to: Company performance, Economic conditions, Interest rates, Industry developments, Investor sentiment, Domestic and global events etc. Equity funds may therefore be more appropriate for investors with suitable risk capacity and longer investment horizons.
- Interest-Rate Risk – Debt mutual funds can be affected by changes in interest rates. When market interest rates change, the prices of existing fixed-income securities may also change. An increase in interest rate decreases the demand of existng debt bonds in the market. The impact depends on factors such as portfolio maturity and the characteristics of the underlying securities.
- Credit Risk – Credit risk refers to the possibility that an issuer of a debt security may fail to meet its obligations. Debt-oriented mutual funds may invest in securities issued by different entities with varying levels of credit quality. Investors should therefore understand the credit profile of the fund’s portfolio.
- Liquidity Risk – Liquidity risk occurs when securities cannot be easily bought or sold at reasonable prices. Although mutual fund units may generally provide redemption facilities subject to scheme terms, the underlying securities may have varying levels of liquidity. Investors should understand the applicable exit conditions, settlement process, and any exit load.
- Inflation Risk – Inflation reduces the purchasing power of money over time. An investment may generate a positive nominal return but still provide limited growth in real purchasing-power terms if inflation is high. Long-term investors should therefore consider whether their investment strategy has the potential to keep pace with their financial objectives and inflation.
Types of Mutual Fund
Mutual funds can be classified in several ways. Investors should understand the primary categories before selecting a scheme. These are –
1. Equity Mutual Funds
Equity mutual funds invest predominantly in equity and equity-related securities. They are generally intended for investors seeking long-term capital appreciation and who can tolerate market volatility. Major equity-oriented categories may include:
- Large-Cap Funds – These funds primarily invest in larger, established companies.
- Mid-Cap Funds – These focus primarily on medium-sized companies and can have higher volatility than large-cap-oriented investments.
- Small-Cap Funds – These invest primarily in smaller companies and can experience significant fluctuations and higher risk.
- Large & Mid-Cap Funds – These combine exposure to large and mid-sized companies according to the scheme’s mandate.
- Multi-Cap Funds – These invest across large-, mid-, and small-cap segments subject to applicable regulatory requirements.
- Flexi-Cap Funds – These provide the fund manager flexibility to invest across different market-capitalisation segments.
- Sectoral Funds – These concentrate investments in a particular sector. Because of their concentration, sectoral funds may involve higher concentration risk.
- Thematic Funds – These invest around a particular investment theme and may also carry significant concentration risk.
Equity funds generally require a sufficiently long investment horizon because short-term market fluctuations can be substantial.
2. Debt Mutual Funds
Debt mutual funds primarily invest in fixed-income securities. These may include:
- Government securities
- Treasury-related instruments
- Corporate bonds
- Commercial paper
- Certificates of deposit
- Other permitted debt and money-market securities
Debt funds can differ significantly in terms of duration, credit quality, and interest-rate sensitivity. Potential risks include:
- Interest-rate risk
- Credit risk
- Liquidity risk
- Reinvestment risk
Therefore, investors should not assume that every debt mutual fund is low-risk.
3. Hybrid Mutual Funds
Hybrid funds invest in a combination of asset classes, commonly equity and debt. They are designed to provide a combination of growth and income or stability depending on the specific scheme. Different hybrid categories can have substantially different equity and debt exposures. Examples include:
- Conservative-oriented hybrid funds
- Balanced-oriented categories
- Aggressive hybrid funds
- Dynamic asset allocation or balanced advantage funds
- Equity savings funds
- Multi-asset allocation funds
The risk level depends on the underlying asset allocation and investment strategy.
4. Index Funds
Index funds attempt to replicate or track a specified market index. Instead of actively selecting securities to outperform a benchmark, the fund generally follows the composition and methodology of the relevant index.
Advantages can include:
- Broad diversification
- Rules-based investing
- Relatively simple strategy
- Potentially lower portfolio turnover
However, index funds remain market-linked investments and can decline when the underlying index falls.
5. Exchange-Traded Funds
Exchange-Traded Funds, or ETFs, are investment funds whose units are traded on stock exchanges. They may track:
- Equity indices
- Bonds
- Gold
- Other permitted assets or indices
ETFs combine features of investment funds and exchange-traded securities. Investors should consider trading liquidity, brokerage costs, tracking differences, and other applicable expenses.
6. Fund of Funds
A Fund of Funds invests primarily in other funds rather than directly investing in individual securities. This structure can provide access to specific investment strategies or markets through underlying funds.
Investors should understand the expenses and risks at both the fund and underlying-fund levels.
7. Solution-Oriented Mutual Funds
Some mutual fund categories are designed around specific long-term objectives such as:
- Retirement planning
- Children’s financial goals
These products may have specific conditions or restrictions according to the scheme. Investors should carefully review the scheme documents before investing.
8. Tax-Saving Mutual Funds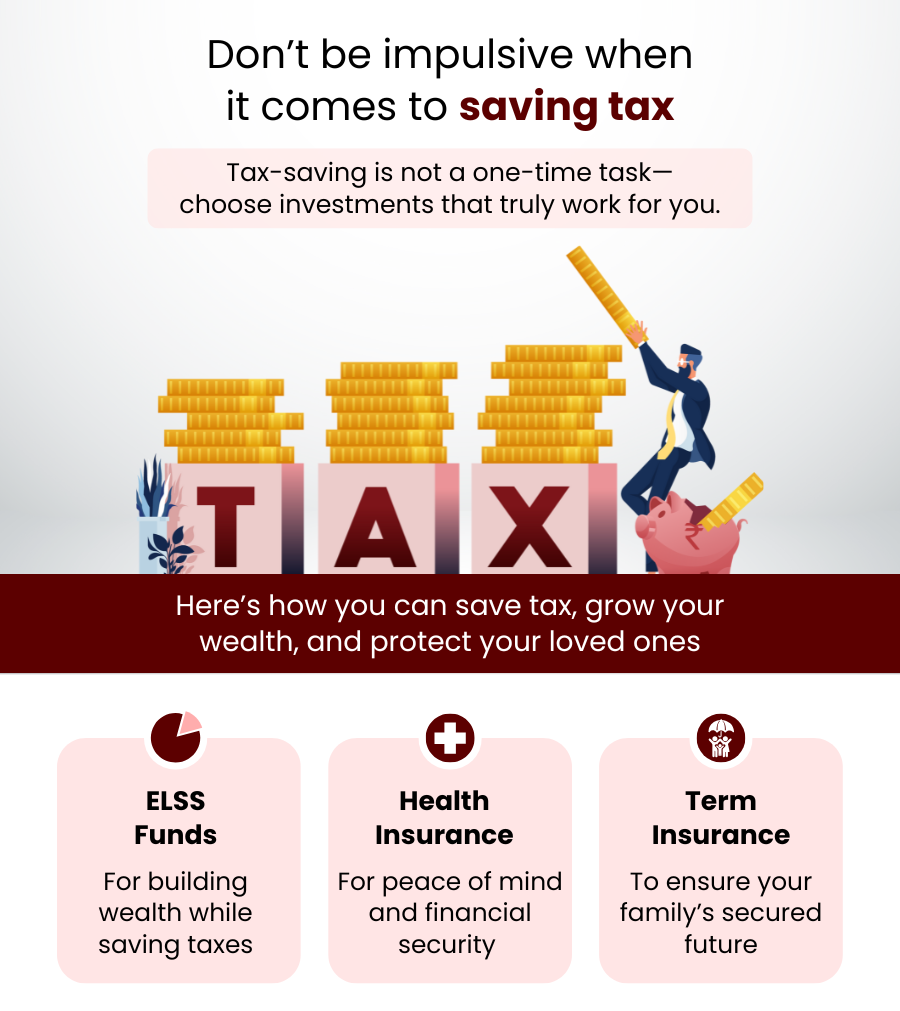
Certain mutual fund schemes, such as Equity Linked Savings Schemes (ELSS), are designed to provide tax-related benefits under applicable provisions of Indian tax law.
ELSS is equity-oriented and therefore subject to market risk.
Tax benefits, eligibility, holding conditions, and applicable rules can change, so investors should verify the current tax provisions before investing.
Selection of Right Mutual Fund
Before investing, for selection of mutual fund scheme consider the following factors.
- Define the Goal – Determine why the investment is being made.
- Determine the Time Horizon – Understand when the money will be required.
- Assess Risk Capacity – Determine how much loss can financially be tolerated.
- Assess Risk Tolerance – Understand how much volatility the investor is psychologically comfortable with.
- Understand the Fund Category – Know what the scheme invests in and how it generates potential returns.
- Review Portfolio Characteristics – Examine the underlying holdings, asset allocation, concentration, duration, and credit profile where relevant.
- Consider Costs – Review applicable expense ratios, exit loads, transaction costs, and taxation.
- Review Performance – Past performance can provide information but does not guarantee future returns.
Performance should be considered across appropriate periods and against relevant benchmarks and peers.
Investing through SIP
SIP is one of the most popular methods of investing in mutual funds. Instead of investing a large amount at once, investors contribute regularly. For example, an investor may establish a monthly investment toward a long-term goal.
Potential benefits of SIP include:
- Financial discipline
- Regular investing
- Reduced dependence on market timing
- Long-term wealth-building approach
- Averaging of cost of investment
However, SIP is a method of investing, not a guarantee of returns.
Investment and Diversification
Mutual funds can provide diversification within a particular investment category. For example, an equity fund may hold multiple companies. However, investors should also consider diversification between fund categories and asset classes. Owning several funds does not automatically mean having a diversified portfolio.
If multiple funds hold similar securities, the investor may still have substantial concentration. Therefore, portfolio diversification should be evaluated based on the underlying exposures rather than simply the number of mutual fund schemes owned.
Specialized Investment Fund (SIF)
Specialized Investment Fund (SIF) is a regulated investment product that provides investors with investment strategies that may be more specialised than those generally available through conventional mutual fund schemes. SIFs are designed to offer greater flexibility in portfolio construction and investment strategies, subject to the applicable regulatory framework.
- Minimum investment required is Rs. 10 Lakhs
- Depending on the SIF strategy, investments may be made across permitted asset classes and securities, with the objective of following a defined investment approach.
- SIFs may be considered by investors seeking a more specialised investment solution and who understand the associated market risks.
- SIF can be considered as one component of a diversified investment portfolio, depending on an investor’s individual circumstances.
Before investing, investors should consider their financial goals, risk tolerance, investment horizon, liquidity needs, investment strategy, costs, and applicable eligibility requirements.
Portfolio Management Services (PMS)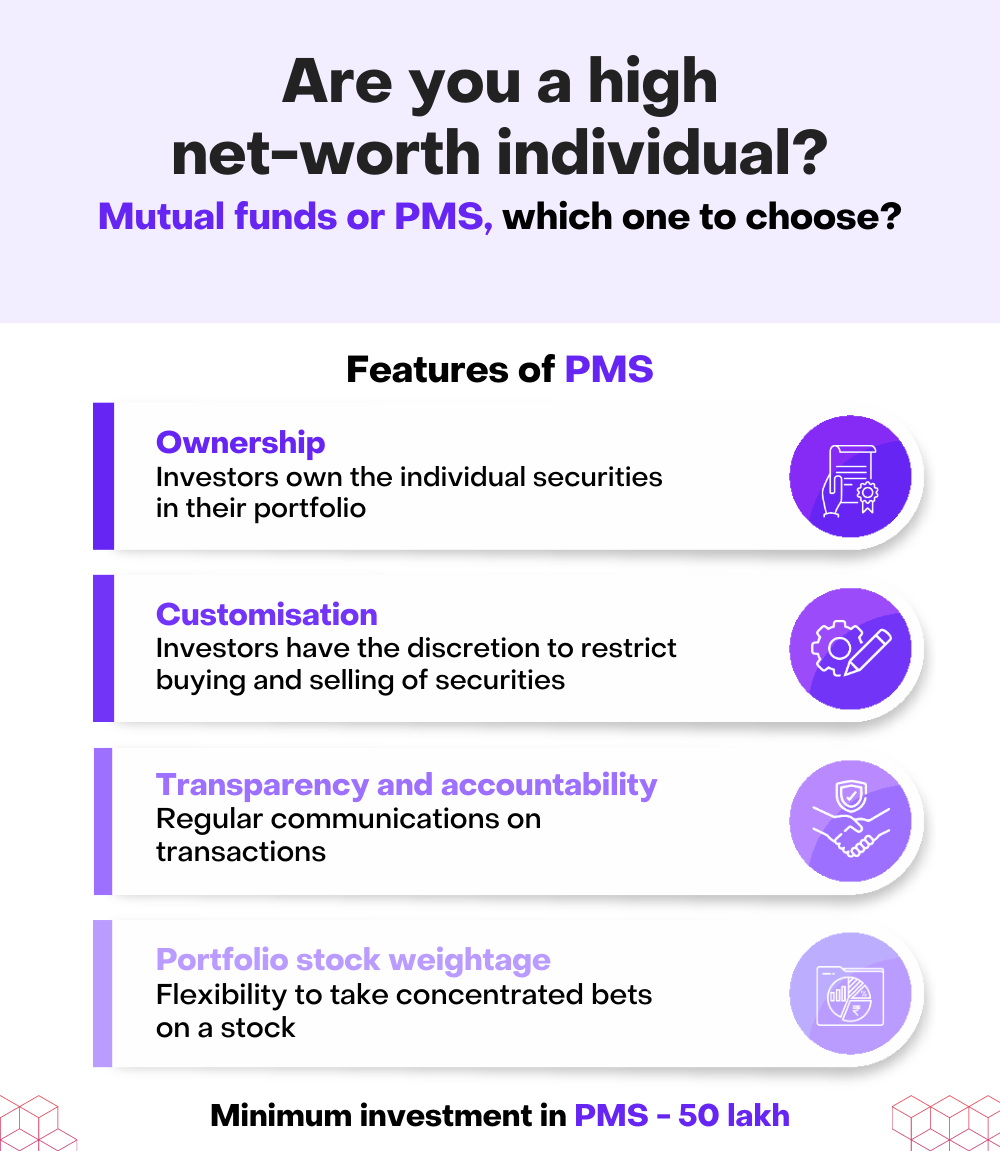
Portfolio Management Services (PMS) is a professionally managed investment service designed for investors who seek personalised portfolio management. Under PMS, an authorised portfolio manager manages a portfolio of securities on behalf of the client according to the agreed investment strategy and applicable regulations.
- Minimum investment required in PMS is Rs. 50 Lakhs.
- PMS may invest in assets such as equities, debt securities, and other permitted instruments, depending on the selected strategy. Unlike a mutual fund, where investors generally hold units of a pooled fund, PMS provides a more individualised portfolio structure for each client.
- PMS can offer features such as professional portfolio management, strategy-based investing, portfolio monitoring, and personalised investment approaches. However, PMS investments involve market risk, and portfolio values can fluctuate.
- PMS is generally suited to investors who understand market risks and meet the applicable eligibility and regulatory requirements.
Alternative Investment Fund (AIF)
Alternative Investment Funds (AIFs) are privately pooled investment vehicles established to invest in a defined investment strategy and are regulated under the applicable SEBI framework in India. AIFs can provide access to investment opportunities and strategies that may differ from those typically available through conventional mutual funds.
- Minimum investment required in AIF is Rs, 1 Crore.
- AIFs are broadly classified into Category I, Category II, and Category III, with each category covering different types of investment strategies and structures.
- Depending on the fund’s mandate, an AIF may invest in areas such as start-ups, private companies, real estate-related opportunities, debt instruments, equities, or other permitted investments.
- AIFs may offer portfolio diversification and access to specialised strategies, but they can also involve higher complexity, market risk, liquidity risk, and other investment-specific risks.
Common Mistakes in Mutual Fund Investment
The common mistakes that individual investors generally do while selecting investment options in practice are found as –
- Chasing Past Returns – A fund that performed well in the past may not continue to outperform.
- Selecting Funds based on Ratings – Ratings and rankings should not replace proper financial analysis.
- Investing without a Goal – Every investment should ideally have a defined purpose.
- Over-Diversification – Holding too many similar funds can make a portfolio unnecessarily complicated.
- Ignoring Risk – Higher return potential generally comes with greater uncertainty.
- Panic Selling – Short-term market declines can lead to emotionally driven decisions.
- Stopping SIPs during Market Corrections – Market conditions should be evaluated in the context of the financial goal rather than reacting emotionally to short-term movements.
- Ignoring Taxation and Costs – Investment returns should be evaluated after considering applicable expenses and taxes.
Role of a Good Financial Planner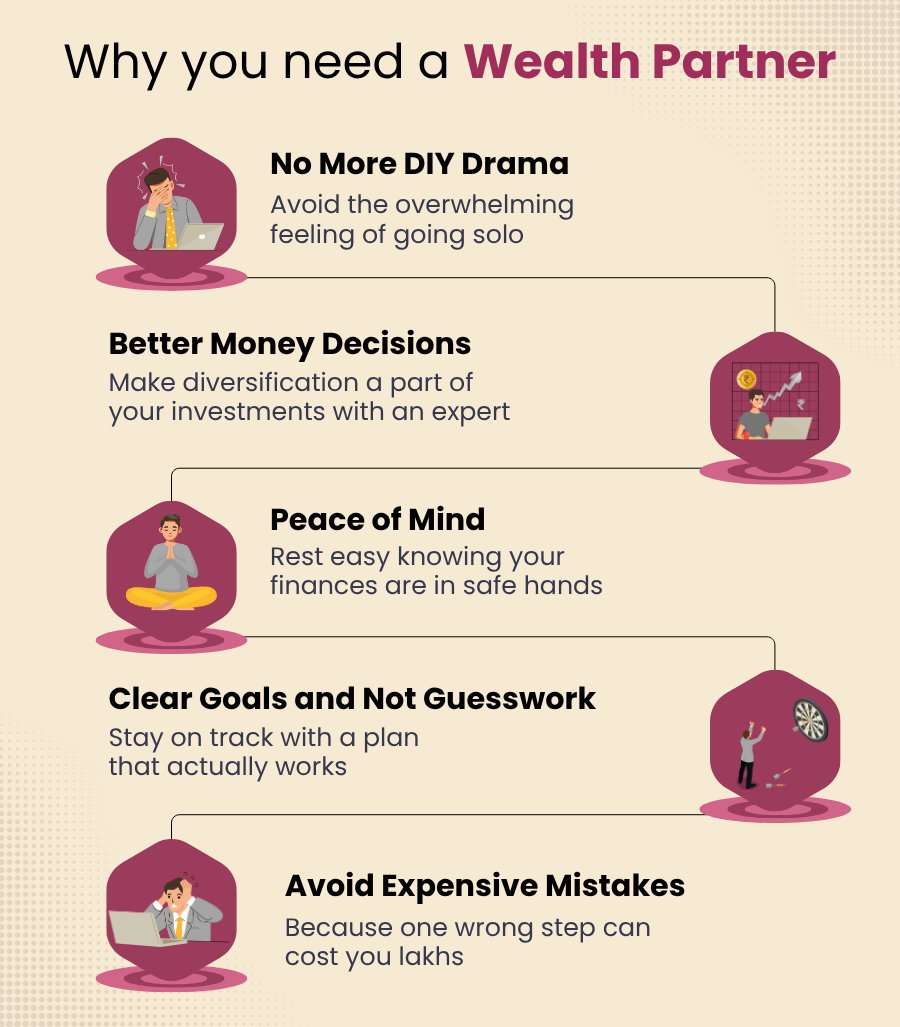
A financial planner can help investors integrate mutual funds into a broader financial strategy. The process may include:
- Understanding financial objectives
- Assessing current financial position
- Determining risk tolerance and capacity
- Establishing an appropriate asset allocation
- Selecting suitable investment categories
- Creating goal-based investment plans
- Monitoring portfolio performance
- Rebalancing when appropriate
- Reviewing financial goals periodically
The planner’s role should be broader than simply recommending a mutual fund.
Conclusion
Mutual funds can play an important role in a diversified financial plan, but they are not risk-free products. Their suitability depends on the underlying assets, investment strategy, time horizon, risk profile, and financial objectives of the investor.
- Equity mutual funds may provide long-term growth potential but can experience substantial market volatility.
- Debt funds may offer exposure to fixed-income markets but can face interest-rate, credit, and liquidity risks.
- Hybrid funds combine asset classes and therefore have their own risk-return characteristics.
- Index funds, ETFs, Fund of Funds, solution-oriented funds, and tax-saving funds serve different purposes and should be evaluated individually.
A disciplined approach should include goal-based investing, suitable asset allocation, diversification, systematic investing where appropriate, risk assessment, cost awareness, periodic review, and behavioural discipline.
Mutual funds can be valuable tools for wealth creation and financial planning when used appropriately. However, investors should understand that market-linked investments can lose value and that past performance does not guarantee future results.
Understand the Goal. Understand the Risk. Choose the Right Category. Invest with Discipline. Review Regularly.
Disclaimer: This article is intended for general educational and awareness purposes only and does not constitute personalized financial, investment, insurance, tax, or legal advice.
Mutual fund investments are subject to market risks, including the possible loss of principal. Different mutual fund schemes carry different levels and types of risk. Past performance does not guarantee future results. Investors should carefully read the relevant Scheme Information Document, Key Information Memorandum, and other applicable documents and consult an appropriately qualified and authorized financial professional before making investment decisions.
— Admin —